The Overstock Reckoning: Unlocking the Working Capital Trapped in Your Warehouse
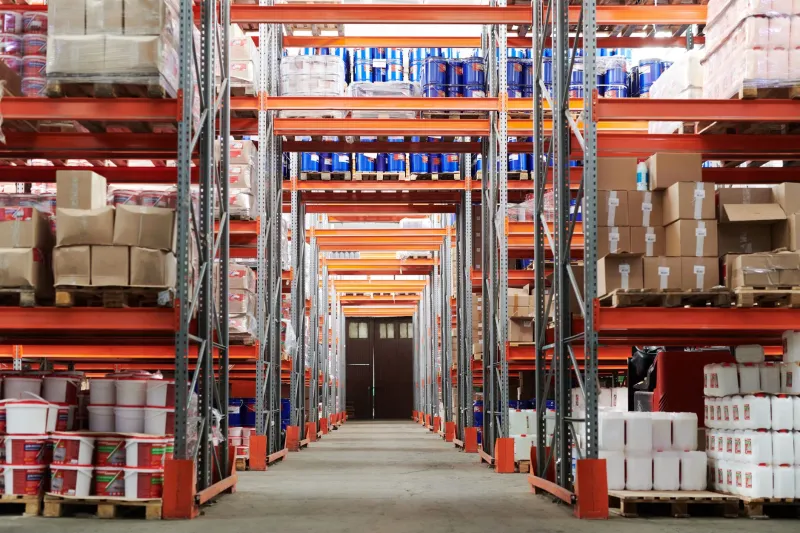
Walk through the back sections of nearly any US manufacturing facility and you will find it: shelving units holding material ordered for a program that was cancelled, spools of wire gauge that no current product requires, structural profiles purchased speculatively ahead of a price increase that never sustained. It sits quietly, occupying space, tying up capital, and appearing on balance sheets as an asset that functions, in practice, more like a liability.
Excess and obsolete inventory—commonly abbreviated in operations circles as E&O—is among the most widespread and least-discussed sources of financial drag in American manufacturing. Industry estimates suggest that US manufacturers collectively hold hundreds of billions of dollars in inventory that turns fewer than twice per year, with a meaningful fraction turning not at all.
The costs extend well beyond the purchase price of the material itself.
Quantifying What 'Dead' Inventory Actually Costs
Most finance teams recognize the direct cost of excess inventory: the capital deployed to purchase it, which cannot be redeployed until the material moves. What is less consistently measured is the full carrying cost burden that accumulates while that material sits.
Industry benchmarks place total inventory carrying costs—encompassing warehouse space, insurance, handling labor, obsolescence risk, and the opportunity cost of tied-up capital—at between 20 and 35 percent of inventory value per year. For a manufacturer holding $2 million in slow-moving stock, that implies an annual carrying burden of $400,000 to $700,000, independent of any write-downs.
Obsolescence risk compounds the calculation further. Materials held for 18 months or longer face meaningful probability of specification changes, shelf-life expiration, corrosion, or technological obsolescence that render them unsalable at full value—or unsalable at all. The longer excess inventory ages, the less recoverable its value becomes.
A 2024 operational review published by a Midwest automotive components supplier found that 34 percent of their raw material inventory had not moved in over 12 months. Of that fraction, the company ultimately recovered an average of 41 cents on the dollar through liquidation—compared to the 70 to 80 cents recoverable had disposition occurred within six months of the material being flagged as slow-moving.
Timing, as that case illustrates, is central to recovery value.
How Manufacturers Are Recovering Value: Three Proven Approaches
The strategies US manufacturers are deploying to address excess inventory span a spectrum from technology-driven prevention to market-based liquidation.
Inventory Optimization Software
The most structurally impactful intervention is reducing the rate at which excess inventory accumulates in the first place. A growing number of mid-market manufacturers have implemented demand-driven inventory optimization platforms that replace static min/max reorder parameters with dynamic models incorporating real demand signals, supplier lead time variability, and carrying cost inputs.
The practical effect is a reduction in safety stock buffers that were historically set conservatively—and rarely revisited. One Ohio-based precision machining operation reported a 22 percent reduction in average raw material inventory value within nine months of implementing a demand-sensing platform, with no increase in material shortages. The freed capital was redeployed into equipment upgrades that had been deferred for two fiscal years.
These platforms vary considerably in sophistication and price point. Cloud-based solutions with subscription pricing have made inventory optimization accessible to manufacturers operating well below the enterprise scale at which such tools were historically viable.
Secondary Marketplaces and Peer-to-Peer Liquidation
For inventory that has already accumulated, secondary industrial marketplaces represent one of the highest-recovery-value disposition channels available. Unlike traditional scrap or liquidation auctions—which typically return 10 to 30 percent of original material cost—peer-to-peer industrial marketplaces connect sellers of excess material directly with manufacturers who can use it in production, often recovering 50 to 75 percent of original value.
The logic is straightforward: a roll of 304 stainless steel sheet that is excess to one fabricator's needs may be precisely what a neighboring manufacturer requires for an active production run. The challenge has historically been connecting those two parties efficiently. Digital industrial marketplaces are solving that matching problem at scale.
Several US-based platforms now specialize in excess industrial materials, offering searchable listings by material specification, form factor, quantity, and geography. Listing fees are typically modest, and transaction volumes on these platforms have grown substantially as procurement teams have become more comfortable sourcing from secondary channels.
Strategic Liquidation Partnerships
For manufacturers with large volumes of excess inventory—or material categories that are difficult to move through peer-to-peer channels—structured partnerships with industrial liquidators offer a faster, if lower-recovery, path to disposition.
The key distinction between effective and ineffective liquidation is the degree to which the manufacturer controls the process. Manufacturers that engage liquidators reactively, after material has aged significantly and options have narrowed, consistently recover less than those that establish standing liquidation agreements with predefined trigger criteria—for example, any inventory item that has not moved in 180 days is automatically evaluated for disposition.
Some manufacturers have formalized this further by creating internal excess inventory review committees that meet quarterly, with explicit authority to authorize disposition below book value when carrying cost analysis demonstrates that liquidation is financially superior to continued holding.
Actionable Steps for Procurement and Operations Teams
For organizations ready to address excess inventory systematically, the following sequence provides a practical starting framework.
Step one: Conduct a full inventory age analysis. Segment all raw material and component inventory by last movement date. Identify everything that has not moved in 90, 180, and 365 days. This single exercise typically reveals the scope of the problem with clarity that surprises most leadership teams.
Step two: Calculate full carrying cost by segment. Apply a carrying cost rate—industry standard is 25 to 30 percent annually—to each aging segment. This converts the inventory problem from a unit count to a dollar figure that finance leadership can engage with directly.
Step three: Evaluate disposition options by recovery value. For each aging segment, assess recovery value across available channels: internal consumption, peer-to-peer marketplace, structured liquidation, and scrap. Prioritize disposition through the highest-recovery channel available within an acceptable time horizon.
Step four: Implement trigger-based review processes. Establish standing criteria that flag inventory for disposition review automatically, preventing future accumulation from aging unnoticed.
The capital locked in excess inventory is not permanently lost. It is recoverable—with the right tools, the right channels, and the organizational discipline to act before time erodes the options.